At a glance
Gross yield divides annual rent by the price; net yield is what reaches your account after vacancy, running costs, management and tax. In the worked example below — a €200,000 apartment in Torrevieja — 7.7% gross becomes 1.5% net.
Every brochure for a Costa Blanca rental property quotes a yield. Almost none of them quote the net yield — the number that actually arrives in your bank account at the end of the year. The gap is rarely small. In the worked example below, a €200,000 apartment in Torrevieja, the brochure says 7.7% and the bank account says 1.5%. That is the gap this piece exists to close.
The brochure number — gross yield
Gross yield is the simplest possible calculation: annual rental income divided by purchase price. A €200,000 apartment renting at €1,400 per month for 11 months produces €15,400 of annual income, a gross yield of 7.7%.
Brochures stop here. Sometimes they stop one notch earlier and quote peak monthly rent multiplied by 12, which inflates the number by another point. The 7.7% becomes a 9% headline. Both numbers are useless for decision-making because they ignore everything that happens between the tenant's payment and your bank balance.
What the gross figure leaves out
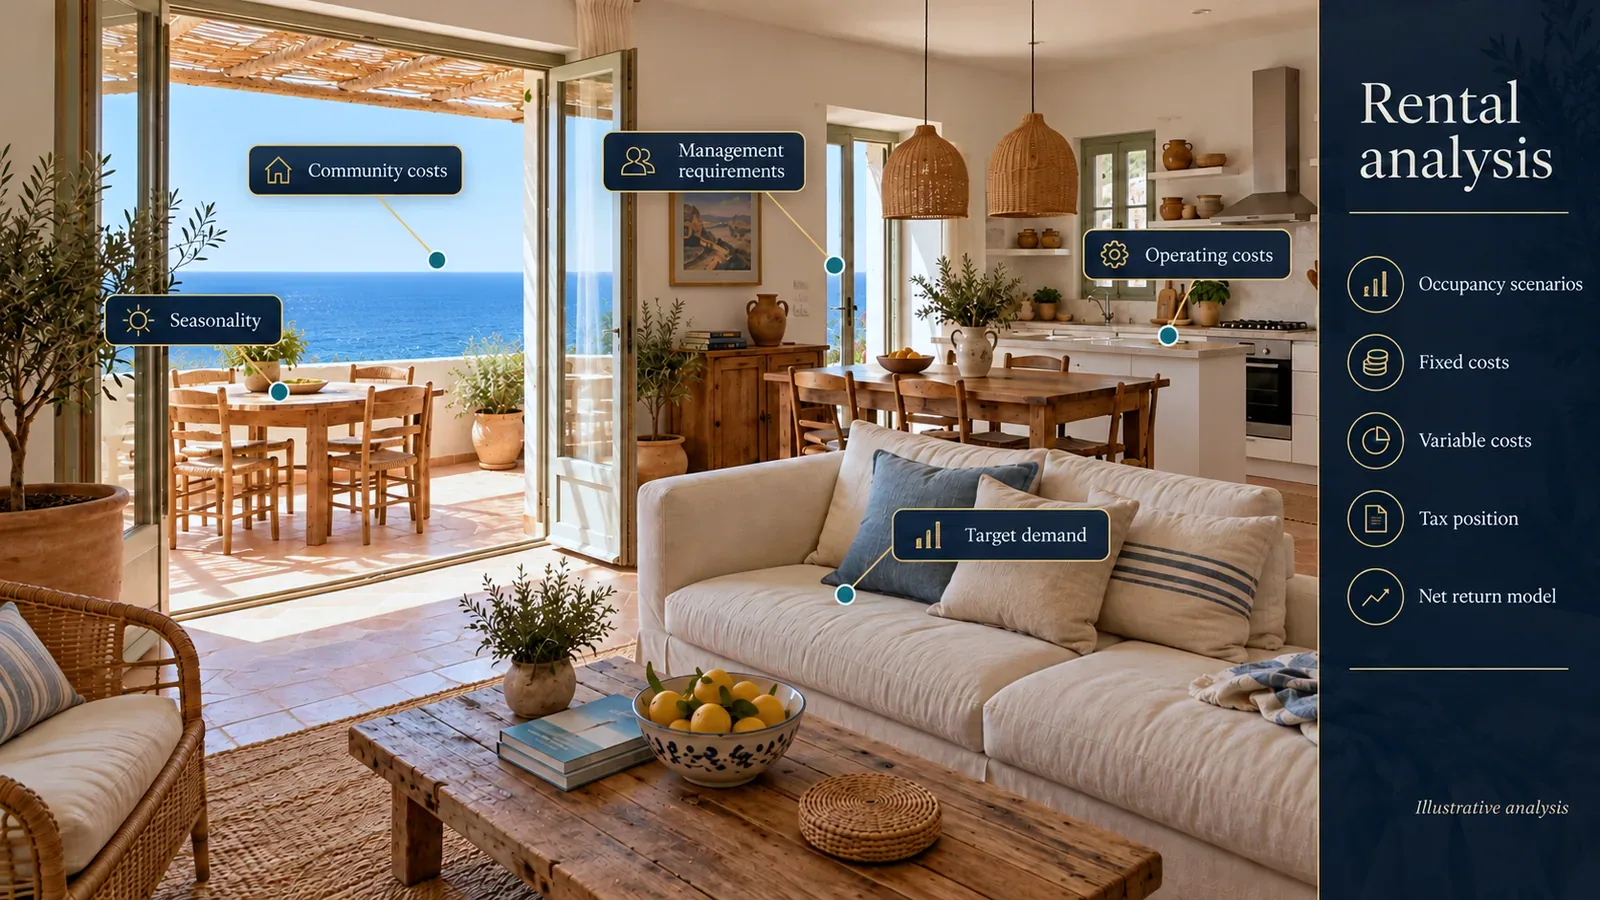
Below is the actual deduction stack on the same apartment. Numbers are illustrative, drawn from a typical Torrevieja two-bedroom in a well-run urbanisation, mid-tier furnishing, mixed short-term and long-term rental. Yours will differ — but the categories will not.
Acquisition costs spread over a 10-year hold
You pay them once at purchase but they erode the yield from year one. ITP at 9% of the price (the general rate in the Valencian Community; check the rate in force on your completion date), notary and registry around €1,900, plus any legal and tax advice you take, which depends on its scope. Leaving the advice aside, that is roughly €19,900 on a €200k purchase (€18,000 + €1,900), or about €2,000 per year of drag if you intend to hold for 10 years.
The waterfall below shows the annual cash flow only. It does not deduct this acquisition drag, which would lower the return further.
Annual operating costs
- IBI (council tax): €380–€520 depending on cadastral revision year.
- Community fees: €1,200–€2,400 in a typical urbanisation with a pool.
- Property insurance: €280–€450.
- Maintenance reserve: rule of thumb 1% of the property value annually for repairs and replacements. €2,000 on a €200k property. A reserve is cash set aside, not a tax-deductible expense; for EU/EEA residents, repairs are deductible when they are actually incurred.
- Utilities (when units are rented short-term): €1,400–€1,800 — standing charges plus consumption that cannot be re-invoiced to short-stay guests.
- Cleaning & turnover: €25–€55 per turnover. At 30 stays a year, €900–€1,650.
Add a ten percent vacancy assumption — €1,540 in lost rent — and a rental-management fee if you are using a property manager (typically 18–25% of rent on short-term, 8–12% on long-term).
The tax layer
As I explain in my Modelo 210 piece, the rate depends on whether you can deduct expenses. EU/EEA non-residents pay 19% on net rental income; everyone else pays 24% on gross. On the same flat, that produces meaningfully different bottom lines.
The full waterfall — Dutch buyer, full year
| Line | Amount |
|---|---|
| Gross rental income | €15,400 |
| Less: vacancy assumption (10%) | −€1,540 |
| Effective rental income | €13,860 |
| Less: IBI | −€450 |
| Less: community fees | −€1,800 |
| Less: insurance | −€340 |
| Less: maintenance reserve (1%) | −€2,000 |
| Less: utilities net of guest reinvoice | −€1,500 |
| Less: cleaning & turnover | −€1,200 |
| Less: management fee (20% of effective) | −€2,772 |
| Pre-tax cash income | €3,798 |
| Less: Modelo 210 (19% on deductible base) | −€722 |
| Net cash to owner | €3,076 |
| Net yield on €200,000 purchase | 1.5% |
Illustrative. For simplicity, the Modelo 210 line applies 19% to the pre-tax cash income shown above.
Brochure: 7.7%. Reality: 1.5%. That is not a math trick — it is the standard Costa Blanca outcome on a furnished apartment in mixed rental, with one tenant, professionally managed. The arithmetic improves with longer-term tenants (lower turnover and management cost), with self-management (savings of 18–22% of rent), and with a property purchased at a price below market.
On a Costa Blanca rental property, breakeven net yield against an ETF benchmark is roughly 4.5–5%. To get there, you have to act on at least two of these four levers: longer rental terms, below-market entry, leverage, or self-management. None of them appear in the brochure. All of them appear in a proper cash-flow analysis.
How to read a brochure from now on
When the agent quotes 7%, ask three questions:
- Is that gross or net? If they hesitate, gross.
- What occupancy rate is assumed? Anything above 85% is optimistic in most coastal sub-markets.
- Are taxes included? Not in the headline figure they aren't.
The answers will not change the property — but they will change what you offer for it.
Free checklist · 1-page PDF
Free checklist: five documents to check before the arras
The five documents in the order to read them, with what to look for in each. One page you can print or keep on your phone.
Thank you. Your checklist is ready.
Download the checklist (PDF)One page, A4. I may also email you about your purchase, as you agreed.
Sources
- Modelo 210 — filing periods (plazo de declaración) · Agencia Tributaria (AEAT) · checked 2026-10-07
- Non-resident tax on rented property · Agencia Tributaria (AEAT) · checked 2026-10-08